FREE GUIDE FOR CANADIAN HOMEOWNERS
Good Income. Tight Month. Find Out Why in 6 Minutes.
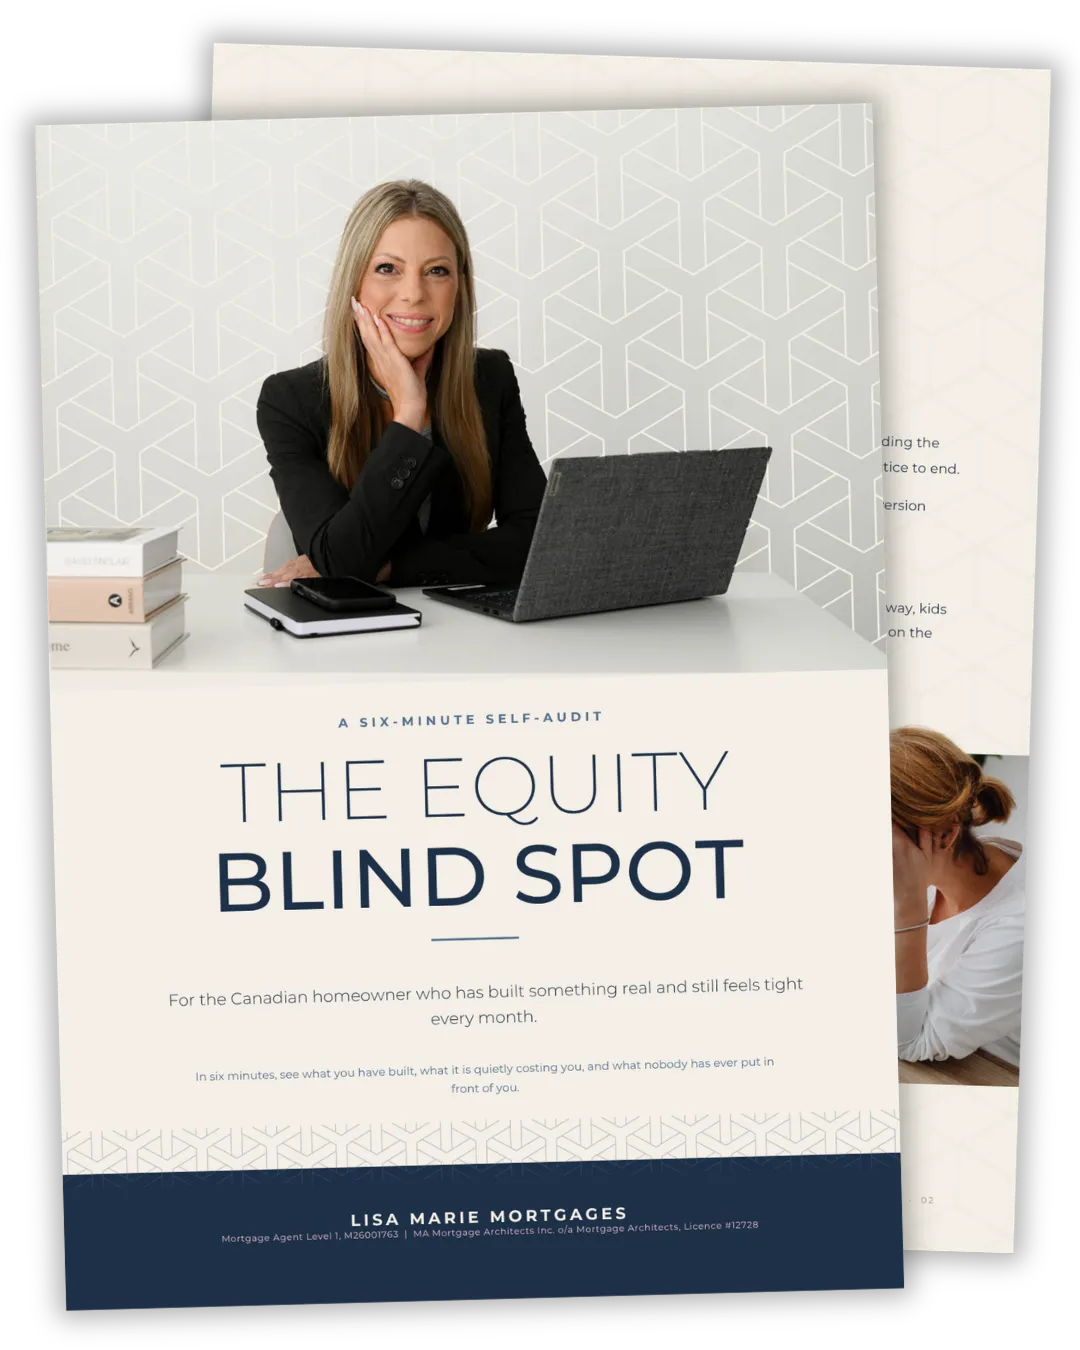
Get The Equity Blind Spot, the 6-minute self-audit for Canadian homeowners who earn well and still feel it by the last week of the month. Ten questions you can answer from memory. You walk away with the 2 numbers you have never seen side by side.
FREE GUIDE FOR CANADIAN HOMEOWNERS
Good Income. Tight Month.
Find Out Why in 6 Minutes.
Get The Equity Blind Spot, the 6-minute self-audit for Canadian homeowners who earn well and still feel it by the last week of the month. Ten questions you can answer from memory. You walk away with the 2 numbers you have never seen side by side.
FREE GUIDE FOR CANADIAN HOMEOWNERS
Good Income. Tight Month. Find Out Why in 6 Minutes.
Get The Equity Blind Spot, the 6-minute self-audit for Canadian homeowners who earn well and still feel it by the last week of the month. Ten questions you can answer from memory. You walk away with the 2 numbers you have never seen side by side.
Here's an example for you...
$37,500 carried at 20% costs about $625 a month in interest before one dollar touches the balance.
*Illustration only, using simple monthly interest. Your figures will differ.
WHAT YOU'LL LEARN
Why the tight feeling has an explanation
You are careful. You pay on time. Understand the real reason the last week of the month still feels the way it does, and put down the idea that you did something wrong.
The 2 numbers that have never been put together
What your home has built for you, and what you pay to carry everything else. See why these have always been looked at separately, and what changes when they sit side by side.
Your Margin Gap
A simple way to see roughly what your current setup costs every month. No statements. No calculator. Most people guess low.
The rule you were taught, and where it stops
"Never touch your equity" is an incomplete rule. Understand the difference between equity that is protected and equity that is simply sitting idle.
I rebuilt the structure on my own home in 2016.
Same income. Different month.
Lisa Marie Voth, Mortgage Agent Level 1. Licensed in Ontario and Manitoba.
WHO THIS GUIDE IS FOR
Canadian homeowners who earn well and still feel tight by the last week of the month
Families whose mortgage, savings, cards, and line of credit sit in three or four different places
People who have built real equity in their home and have never been shown what it could do
Anyone who got a good rate, pays on time, did everything right, and still cannot work out why it feels like this
WHY YOU NEED THIS GUIDE
Most Canadian homeowners have never had one person look at the whole picture.
Your bank handles the mortgage. Someone else has the card. The dealership did the car.
Each one is responsible for a single piece, and the whole picture sits outside all of their jobs.
That is the Blind Spot.
It was built into the system before you got here.
This guide is the first real look at it.
WHY I WROTE THIS
In 2016, I went back to work as a single parent with two kids and a house I owned on my own.
There was a stretch near the end of every month where I did the arithmetic more than once, hoping it would come out kinder the second time.
I was careful with money. I tracked things. I stayed inside my means.
What I was missing was a structure that fit the life I was actually living.
So I changed the structure. The pieces started working with each other instead of against each other.
"Why am I only seeing this now?"
That question is the reason I wrote this guide.
The rate matters. It comes fourth.
So, Where Do I Stand on This?
Almost every mortgage conversation in this country opens with a rate. I think that is the wrong first question.
A rate is one variable sitting inside a structure. When the structure was never built around your household, a sharper rate makes an awkward arrangement slightly cheaper to run. Your month still feels the same on the 22nd.
So I start with the month. What comes in. What goes out. What it costs you to carry what you carry. Where the equity you have built actually sits inside all of it.
This guide is the first step of that. Read it and you will understand your own setup better than most people ever do, whether you and I ever speak or not.
WHAT'S INSIDE
The Blind
Spot
Why your equity and your debts have always been looked at separately, and what it costs to keep them apart.
Why You Haven't Fixed This Yet
The advice you were given was reasonable and incomplete. Here is the piece that was missing.
The 6-Minute Assessment
Ten questions you answer from memory at your kitchen table. No statements. No logins. Your answers stay with you.
Your Score,
Explained
Three honest profiles. Find out which one is yours and what it means.
Your Margin
Gap
A rough monthly figure for what your current setup costs to run. Almost everyone guesses low.
The Two Places Equity Belongs
Relief and Reserve. What each one is for, and why one of them needs a date attached to count.
This guide is yours to keep whether we ever speak or not.
There is no call attached to it and nothing to apply for.
This guide is yours to keep whether we ever speak or not.
There is no call attached to it and nothing to apply for.
EVEN IF...
Even if you were told never to touch the equity in your home.
That advice carries real wisdom. This guide explains what it covers and where it stops.
Even if budgeting apps never stuck for you.
This looks at how your pieces are arranged, not at what you spend.
Even if you think you already know your numbers.
Most people who take this find the monthly figure runs higher than they guessed.
Even if you plan to change nothing at all.
Then you will know exactly where you stand, and you can stop wondering.
READY TO SEE WHAT YOU'VE ACTUALLY BUILT?
Download The Equity Blind Spot and find the two numbers you have never seen side by side.
Six minutes. Ten questions. Your kitchen table.
The example at the top of this page costs about $625 a month. Every month it goes unlooked at is another $625.*
*Illustration only, using simple monthly interest. Your figures will differ.
Lisa Marie Mortgages. Lisa Marie Helene Voth, Mortgage Agent Level 1, Licence M26001763. MA Mortgage Architects Inc., operating as Mortgage Architects, Licence #12728
Educational only. This guide is not financial advice, a pre-approval, or an offer of credit. Individual circumstances vary.
Privacy Policy • Terms of Service